Florida’s property frenzy in the 1920s is one of the clearest reminders that markets can feel “certain” right before they break. In a few short years, land changed hands at dizzying speeds, prices raced ahead of reality, and ordinary people were pulled into speculation that looked like a one-way path to wealth.
What makes this story so useful today isn’t just the drama, it’s the pattern. Easy credit, relentless marketing, social proof, and the belief that prices can only rise created the conditions for a spectacular surge. Then, when momentum slowed and unexpected shocks arrived, confidence vanished faster than it formed.
“A boom doesn’t end when people stop believing in it; it ends when the next buyer doesn’t show up.”
Below is a clear, scannable breakdown of how the boom built up, what pushed it over the edge, and what the aftermath changed in Florida for decades.
America’s roaring backdrop and why Florida looked irresistible
The early 1920s in the United States were defined by rising prosperity and cultural energy. More workers had stable employment, and benefits like paid vacations and pensions became more common for many middle- and upper-income households. At the same time, car ownership expanded rapidly, turning long-distance travel into a realistic option for families with time and savings.
Florida benefited directly from this shift. Sun, leisure, and the idea of a “fresh start” made the state feel like a reward, especially for northerners facing colder winters. Miami and other destinations developed reputations for glamor, entertainment, and exclusivity, drawing attention far beyond local demand.
This is where the psychology mattered. When a place becomes a national symbol of leisure and opportunity, the conversation stops being about housing needs and starts being about upside. That mindset helped ignite what many later called the florida boom, where enthusiasm itself became the fuel.
How the frenzy started and why it spread so fast
Florida’s surge wasn’t driven only by retirees or long-term residents. A growing share of buyers were visitors who arrived as tourists and left as investors, convinced they were early to an unstoppable trend. As tourism expanded, land values began to rise quickly, and speculators saw a simple trade: buy today, sell soon at a higher price.
Several forces strengthened the momentum:
- Easier financing: Credit became more available, letting people buy property with limited cash up front.
- Rapid population growth: New arrivals increased pressure on housing supply, making scarcity feel real.
- Aggressive promotion: Newspapers and marketing campaigns amplified the sense that “everyone is getting in.”
- FOMO investing: Stories of quick profits spread northward, creating a self-reinforcing rush of new buyers.
At the peak of the mania, Florida didn’t just feel like a hot market; it felt like the market. In 1922, the Miami Herald reportedly became so thick with property advertisements that it was described as the heaviest newspaper in the world, a vivid sign that selling land had become a statewide obsession.
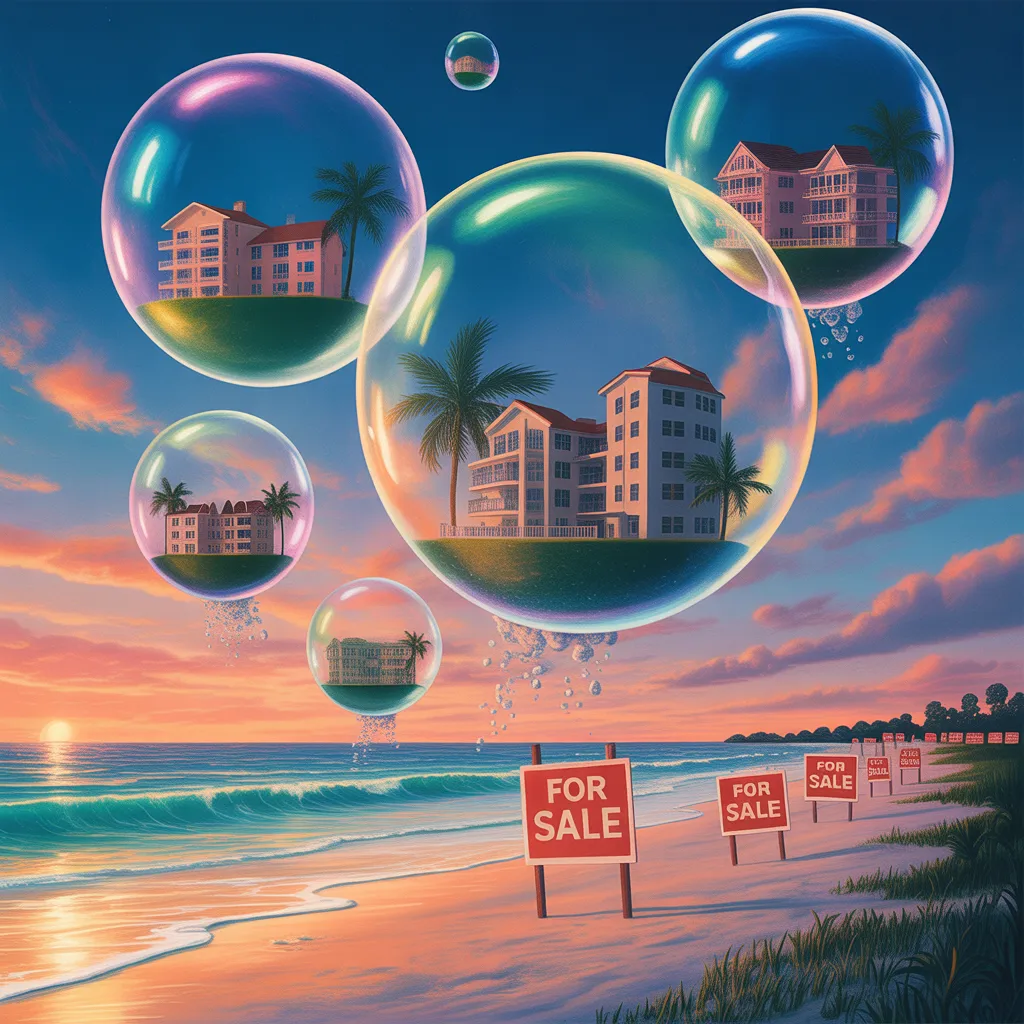
This wasn’t a slow build. It became a national event, often described in hindsight as the real estate bubble in Florida, a moment when demand was driven less by utility and more by belief.
The price spiral and what made it feel “risk-free.”
Boom psychology thrives on numbers, and Florida’s story delivered plenty. As the mid-1920s arrived, land was traded and retraded at higher prices, sometimes in short time spans, as buyers aimed to flip rather than hold. The pattern is familiar: rising prices attract attention, attention attracts capital, and capital pushes prices even higher.
In 1925, the fever reached a level that felt unreal even by today’s standards. Contemporary accounts describe property values in some areas multiplying rapidly, often framed as “doubling and tripling.” In the most extreme anecdotes, prices in parts of the state were described as surging so quickly that values effectively quadrupled in under a year.
One famous example tells of an elderly investor who reportedly bought a parcel for $1,700 and sold it months later for $300,000. Whether every detail of such stories was typical didn’t matter; the stories did the work. They made speculative gains feel normal, and caution feel like missing out.
In bubbles, the most persuasive “data” isn’t a chart, it’s your neighbor’s profit.
This is also where expectations about 1920s house prices became detached from local fundamentals. When buyers believe prices will keep climbing, even a fair price feels cheap compared to tomorrow’s imagined value.
Credit, leverage, and the hidden fragility under the surface
Easy money doesn’t cause every boom, but it changes how booms behave. When credit is plentiful, people can buy more than they otherwise could, and they can buy sooner. That accelerates demand and compresses time, making markets move faster than supply can respond.
Florida’s surge featured a crucial vulnerability: many investors weren’t simply buying land, they were buying it with borrowed money, intending to sell quickly to repay debts and keep the profit. That works only if the next buyer arrives on schedule and at a higher price.
Here’s why that structure is fragile:
- Leverage magnifies outcomes: Small price drops can wipe out thin equity.
- Liquidity depends on optimism: When sentiment shifts, buyers pause, and listings pile up.
- Timing becomes everything: A late-cycle buyer has fewer “greater fools” left to sell to.
This dynamic is a hallmark of the real estate bubble Florida narrative: the market looked strongest right before it became least stable.
The turning point: when momentum slowed, panic did the rest
Bubbles don’t usually pop because one person changes their mind. They pop when a critical mass of new buyers hesitates. In Florida, the slowdown began when prices reached levels that felt too stretched for the next wave of investors. Early buyers started taking profits, and the pool of enthusiastic newcomers thinned.
Once demand cooled, the mechanics flipped:
- Sellers who expected quick resales became desperate to exit.
- Listings rose, price cuts followed, and confidence cracked.
- Highly leveraged owners faced debts that didn’t shrink with market prices.
- “Can’t lose” turned into “can’t sell.”
As the selloff accelerated, more people rushed to offload property, which pushed prices down further. In bubble dynamics, that’s the moment the market stops being a marketplace and becomes an evacuation.
This is why the collapse is often grouped with the Florida real estate boom era: the same forces that lifted prices, optimism, easy financing, and rapid turnover, also made the decline sharp when the story changed.
1926: disaster shocks that deepened the crash
As if financial stress wasn’t enough, Florida faced major external blows that turned a correction into a broader economic crisis. In September 1926, a powerful hurricane hit South Florida with winds reported at around 125 miles per hour. The storm caused severe destruction across a wide area, including Palm Beach County and surrounding communities.
The human and physical toll was enormous. Accounts commonly cite:
- More than 13,000 homes destroyed
- About 415 deaths
- A massive storm surge and widespread flooding are affecting towns such as Belle Glade and Moore Haven.
In practical terms, the hurricane didn’t merely damage buildings. It damaged confidence. Even people who weren’t directly impacted could see that Florida’s “guaranteed paradise” image was vulnerable to reality, especially weather risk and infrastructure limits.
Soon after, another shock arrived: the Mediterranean fruit fly harmed Florida’s citrus industry, adding pressure to a state already struggling with collapsing property values. When a regional economy is overexposed to one booming sector, multiple hits can compound quickly.
This period is central to understanding 1920s Florida beyond the clichés. It wasn’t just a party that ended; it was an economic unraveling that arrived before the rest of the country’s national downturn.
Why Florida slumped before the Great Depression, and what changed
One of the most striking aspects of this story is timing. Florida’s decline began years before the 1929 stock market crash. While much of the country continued enjoying the late-1920s expansion, Florida was already dealing with falling land values, damaged infrastructure, and economic stress.
That earlier collapse shaped Florida’s experience of the later Great Depression. When the national economy fell apart after 1929, Florida had already endured the worst of its property shock. Strangely, that meant the 1929 crash did not land as dramatically in Florida as it did elsewhere, because the state’s boom-and-bust cycle had already run ahead of the national timeline.
This is one reason historians often frame the episode as the Florida land boom of the 1920s, a distinct event with its own arc, drivers, and consequences.
What the aftermath left behind: overbuilding, empty promises, and long-term transformation
The bust didn’t just erase paper wealth. It left visible remnants across the state:
- Overbuilt neighborhoods where demand never materialized
- Unfinished developments and abandoned plans
- Bankruptcies from investors who bought with debt they could no longer service
- Communities forced to rethink growth narratives built on speculation
And yet, the legacy is not only negative. The boom helped accelerate Florida’s transformation into a major destination for tourism and retirement over the long term. Infrastructure, marketing, and national awareness didn’t disappear when prices fell; they reshaped Florida’s identity in ways that later decades would build upon.
This is the paradox of bubbles: they often misallocate capital in the short run, but they can also create foundations that matter later, roads, cities, and industries that survive the collapse. That longer perspective is also why the episode is sometimes remembered as the Florida land boom of the 1920s, a period that pushed growth forward even as it burned many investors along the way.
Practical takeaways: what this boom still teaches about bubbles
You don’t need to invest in property to learn from Florida’s 1920s surge. The same dynamics show up in stocks, crypto, collectibles, and even startup funding cycles.
Here are a few lessons worth keeping in mind:
- A rising narrative can overpower fundamentals until the market runs out of buyers.
- Leverage turns optimism into fragility because debt doesn’t care what your asset is “worth” today.
- Liquidity is not guaranteed; it depends on confidence, and confidence can vanish quickly.
- External shocks matter most when a market is already stretched, because there’s no cushion left.
- Marketing volume can be a warning sign, not a proof of safety.
When everyone can explain why prices must rise, it’s often because risk has been edited out of the story.
Conclusion: a boom that became a blueprint for understanding manias
Florida’s 1920s property surge is more than a historical curiosity; it’s a clean example of how speculation builds, how narratives spread, and how fragile markets become when price depends on perpetual enthusiasm. The boom promised wealth, the bust delivered lessons, and the state carried the consequences long before the rest of the nation faced its own crash.
The big question to leave with is simple: when a market feels “too popular to fail,” are prices being supported by real demand, or by the hope that someone else will pay more tomorrow?